You're busy. We build the portfolio.
Lera Real Estate finds properties with HMO potential, converts them and lets every room, so you can earn strong property income without becoming a developer. You fund the project. We do the rest.
- c.25% cash on cashTarget return, after fees
- Fully hands-offWe manage every stage
- HMO specialistsConversions only
Some deals we've delivered.
HMO specialists who do the hard part for you.
We build HMO portfolios for investors who want the returns without the building sites, paperwork and tenant calls. You stay in control of every key decision. We handle the work, from finding the house to the last tenant moving in.
The property and the profit are 100% yours. We charge a simple 2% acquisition fee and 2% management fee, and the c.25% returns we quote already include them.
From first call to fully let.
We don't buy ready-made HMOs. We find houses that are right for conversion, because that's where the value is created.
- 1
Strategy call
We agree your budget, goals and brief.
Week 1 - 2
Find the house
We source a house with conversion potential and send a full appraisal.
Until the right deal - 3
Purchase
Bought with bridging finance, with solicitors and surveys handled.
Completion - 4
Convert
Planning, licensing and a fully managed build.
Months 1–5 - 5
Let and refinance
Every room let, then refinanced to release your cash.
Month 5–6
Purchase to completed and fully let in around 5–6 months
What could my money return me annually?
Choose an amount and compare what it could earn in a year: in the bank, in a buy-to-let, in the stock market, or in a Lera HMO.
Rates: savings c.5%, London buy-to-let c.5% gross yield, S&P 500 c.10% long-run average, Lera HMO c.25% target after costs and fees. Illustrative only, not a forecast or a guarantee. Unlike a savings account, an HMO is not protected, values and rents can fall, and property can take months to sell.
What's an HMO?How a project pays you back.
Follow an illustrative worked example, based on costs from one of our past projects, from the day we buy to the rent arriving every month.
Illustrative figures onlyTest the numbers yourself
Every deal is different. Move a slider to see how a change in one assumption would affect the worked example above. The figures at the top, every step and the return all update as you go.
What each tenant pays a month, usually with bills included. Higher rent means more profit each year.
What the lender's valuer says the finished HMO is worth. A higher value means a bigger mortgage and more cash back to you.
How much of the new value the mortgage lends. Borrowing more returns more of your cash, but means higher interest.
The yearly interest on the long-term mortgage. HMO rates are currently around 4.5% to 5.75% on a five-year fix.
What our investors say.
The experts on your side, with no stake in your deal.
You could try to build an HMO yourself. Here's why investors choose to have us do it for them.
Equity in your deal
We never take a share of your property or its profits. The house, the rent and the growth are 100% yours. We charge a simple 2% acquisition fee and 2% management fee, already included in every return we show.
Expertise that protects your money
One costly mistake can cost far more than our fees: a layout that fails the council's room sizes, buying where planning won't allow an HMO, a build that overruns, or a down-valuation at refinance. Avoiding those is what we do.
Years of building experience
We've spent years building and delivering high-quality HMO conversions across London, from the first steel to the last tenant moving in. You can see the results in our projects.
A tested, repeatable process
Every project follows the same tested route: source, buy, convert, let and refinance, in around 5–6 months from purchase to fully let.
A trusted team
Our builders, solicitors, brokers and letting agents are people we've worked with project after project, so the work gets done properly and on time.
Total transparency
A full costed appraisal before you commit, weekly photo updates during the build, and clear monthly income statements once it's let.
Know someone who'd love an HMO? Get paid for it.
Refer a friend, client, colleague or relative. We'll pay you 10% of our fees on every property they do with us.
Ready to start your portfolio?
Book a free 30-minute call. We'll talk through your budget and goals, and whether an HMO project is right for you.
Step by step, from first call to first rent.
Seven stages, one team and around 5–6 months from purchase to a finished, fully let HMO. Here is exactly what we do at each stage, what we need from you, and what you get back.
- 7clear stages
- 5–6months, purchase to fully let
- 2+2%our only fees
- 0%of your property or profit
What happens, and who does what.
You stay in control of the big decisions. We do the work in between.
-
01
Discovery call
Week 1A free 30-minute call to understand your budget, goals and timescale, and to check that an HMO project is the right fit for you.
We handle
- Walking you through the full process and the risks
- Explaining costs, fees and finance
- Agreeing a clear investment brief
You decide
- Your budget and target area
- Whether to go ahead
You get A written brief we use to search for your house.
-
02
Sourcing and appraisal
Until the right dealWe look for ordinary family houses with room to convert, because that is where the value is created. Most houses we look at don't make the cut.
We handle
- Searching for and viewing houses
- Checking local planning and HMO licensing rules
- Costing the build and testing local room rents
You decide
- Approve the deal, or pass and wait for the next one
You get A full appraisal for each deal we put forward: layout, costs, rents and expected return.
-
03
Purchase
CompletionWe negotiate the price and buy using bridging finance, so less of your own cash is tied up at the start.
We handle
- Negotiating the offer
- Arranging the bridging loan
- Coordinating solicitors and surveys
You decide
- Fund the deposit and purchase costs
- Sign the purchase documents
You get The house, in your name. Our 2% acquisition fee is paid at this point.
-
04
Design and planning
Month 1We turn the appraisal into a final room layout that meets licensing standards, and get any approvals the conversion needs.
We handle
- Drawings and room layout
- Planning applications, where needed
- Fire safety and licensing requirements
You decide
- Sign off the final layout and specification
You get An agreed plan and build budget before any work starts.
-
05
The build
Months 1–5A fully managed conversion: extensions, new bathrooms, kitchen and finishes. You don't need to visit site or deal with builders.
We handle
- Appointing and managing contractors
- Quality and cost control
- Building control and safety sign-offs
You decide
- Fund the works in agreed stages
- Approve any changes to the budget
You get Regular progress updates with photos.
-
06
Furnish and let
Month 5We furnish every room, advertise and fill the house with vetted professional tenants.
We handle
- Furnishing and final dressing
- Marketing, viewings and tenant checks
- Tenancy agreements and the HMO licence
You decide
- Nothing day to day. We report back as rooms let
You get A finished, fully let HMO.
-
07
Refinance and manage
Month 5–6 onwardsWith the house finished and let, it is revalued as an HMO. A long-term mortgage repays the bridging loan and releases part of your cash.
We handle
- The revaluation and mortgage application
- Repaying the bridging loan
- Ongoing tenants, repairs and compliance
You decide
- Choose the mortgage deal
- Whether to start your next project
You get Cash back from the refinance, then monthly rent and statements. Our 2% management fee is the only ongoing cost from us.
Six months, at a glance.
A typical project from the day we complete on the house. Sourcing comes before this and depends on finding the right deal.
Illustrative. Timings vary with planning, the size of the build and lender processing times.
When cash goes in, and when it comes back.
No surprises. Here is how the funding typically works at each point in the project.
Typical structure, not a quote- At purchase25%
Your deposit, plus stamp duty, legal fees and our 2% acquisition fee. A bridging loan covers the other 75% of the price.
- During the buildStages
You fund the works in agreed instalments as the build progresses, never all up front.
- At refinancec.80%
A long-term mortgage of up to around 80% of the new HMO value repays the bridging loan, and the rest comes back to you.
- Every month afterc.25%
Rent from every room, after the mortgage, running costs and our 2% management fee. That's a c.25% target return a year on the cash left in.
Capital at risk. Returns are targets, not guarantees. Values and rents can fall, and refinance amounts depend on the valuation and lender. See important information.
Start with step one.
Book a free 30-minute discovery call. No obligation, and you'll come away knowing whether an HMO project makes sense for you.
Some deals we've delivered.
Every project starts as an ordinary house and finishes as a fully let, compliant HMO. Tap a project to see the rooms and the numbers.
Want a project like this?
HMOs: what's it all about?
What an HMO is, why it could make your money work more than four times as hard as a savings account or a normal buy-to-let, and how we do all the heavy lifting for you.
Compared with Lera's c.25% target. Capital at risk. Targets and examples are not guaranteed, and past results are not a guide to future returns.
What is an HMO?
A house in multiple occupation is a home rented to three or more people who aren't from the same household and who share facilities like the kitchen. Instead of one family renting the whole house, each tenant rents their own room.
The HMOs we build are aimed at young professionals. Every room has its own en-suite shower room, the kitchens are shared, and bills are usually included, so tenants pay one simple monthly amount.
- Small HMO
- 3–4 tenants. Often allowed without planning permission, unless an Article 4 direction applies.
- Large HMO
- 5 or more tenants. Needs a mandatory council licence, and usually planning permission.
- What tenants get
- A furnished en-suite room, shared kitchens, bills included and a flexible tenancy.
Same house, two ways.
The clearest way to see why HMOs work is to compare one house let two different ways.
HMO rent from the independent valuation of our Greenford UB6 project. Single-let rent is a typical 3-bed listing in UB6. HMOs also have higher running costs, covered below.
What £100,000 could earn in a year.
The same £100,000, four different ways. With a Lera HMO, it could work more than four times as hard as in a savings account or a typical London buy-to-let, though with more risk.
Multipliers compare each option with Lera's c.25% target. Savings: best UK rates, October 2026. Buy-to-let: average London gross yield, before costs (Benham and Reeves, June 2026). S&P 500: long-run average total return in US dollars, which varies a lot year to year (Fidelity). Lera: target cash-on-cash return on the money left in after refinance, after costs and our fees, based on the projects featured on this site (25%–26%). Not guaranteed.
What could your money earn?
Move the slider to your budget and see roughly what it could earn in a year in each option.
Uses the same rates as the chart above: savings c.5%, London buy-to-let c.5% gross, S&P 500 c.10% long-run average, Lera HMO c.25% target after costs and fees. Illustrative only, not a forecast or a guarantee.
Where every pound goes.
Three views of the same worked example, using real costs from one of our projects. Hover over a slice to see the figure.
Worked example: six-room HMO bought for £475,000 with £171,250 of works, valued at £830,000 and refinanced at 80%. The same figures as the step-by-step example on our home page. Returns after costs and Lera's fees; not guaranteed.
How an HMO compares with the alternatives.
Every option has trade-offs. Here's an honest view of each.
| Savings account | S&P 500 fund | London buy-to-let | Lera HMO | |
|---|---|---|---|---|
| Typical yearly return | c.4–5% interest | c.10% long-run average, swings year to year | c.5% gross yield, less after costs | c.25% cash on cash, after costs and fees |
| Where returns come from | Interest | Share prices and dividends | Rent and house prices | Rent by the room, house prices and value created by the conversion |
| Your time | None | None | Tenants, repairs, compliance | Approve the deal, we do the rest |
| A real asset you own | No | No, you own shares | Yes | Yes, a London house |
| Get your cash back | Quickly | Sell any working day | Slow, sell the house | Most of it at refinance, the rest on sale |
| Main risk | Inflation eats the return | Market falls | Empty months and rate rises | Build costs, valuation, rates and regulation |
You invest. We do the rest.
An HMO earns more because it takes more work: finding the right house, planning, building, licensing and letting. That work is exactly what we do, so you get HMO returns without becoming a developer or a landlord.
- Agree your budget and goals
- Approve the deal
- Receive the income
- Area research
- Finding the house
- Full appraisal
- Negotiating
- Bridging introductions
- Solicitors and surveys
- Planning and Article 4
- Layout design
- Building regs
- Managing the builders
- Weekly photo updates
- Fire safety
- HMO licence
- Furnishing
- Certificates
- Photography
- Finding tenants
- Management set-up
- Revaluation
- Refinance support
Why HMOs make a great investment.
Much higher rental income
Letting by the room produces far more rent than letting the whole house, which is what makes returns of around 25% cash on cash possible.
Income from several tenants
With six tenants, one empty room doesn't stop your income. In a single let, one void means no rent at all.
Strong tenant demand
High rents in London mean many young professionals rent a room rather than a whole flat. A quality en-suite room close to transport lets quickly.
Value you create
Converting a house adds rooms, en-suites and income. Lenders value HMOs on what they earn, so a good conversion can be worth much more than it cost.
Cash you can recycle
Once the house is revalued, a refinance can release much of your original cash, ready to fund the next project and grow a portfolio.
A real, physical asset
Your money is in bricks and mortar in London, an asset you own outright, not a share of someone else's fund.
How a conversion adds value.
Our Enfield N9 project shows the effect. Buying the house and converting it cost less than the house was worth once it was finished and let.
See the Enfield projectWhat to watch out for, and how we handle it.
HMOs earn more because they take more work to get right. These are the main things to know.
Licensing and regulation
Large HMOs need a council licence, with rules on room sizes, fire safety and facilities.
Lera: we design every layout to the council's standards and handle the licence application.
Planning and Article 4
Some areas restrict HMOs, and larger ones need planning permission.
Lera: we check planning before we put forward any house.
More management
More tenants means more lettings, more queries and shared spaces to look after.
Lera: we set up professional management so you don't take the calls.
Higher running costs
Bills, furnishing, cleaning and compliance cost more than in a single let.
Lera: every return we quote is after these costs and our fees.
Specialist finance
HMOs need lenders and valuers who understand them, and rates can change.
Lera: we introduce brokers who specialise in HMO bridging and refinance.
Returns aren't guaranteed
Values, rents and interest rates can move against you.
Lera: we build in contingency and only bring you deals that work on cautious numbers.
Ready to make your money work harder?
Book a free call and we'll show you how a project would work with your budget.
We build portfolios the way we'd build our own.
Lera Real Estate is for investors who can see the value in property but don't have the time to create it themselves.
Built on HMOs, because the numbers work.
We focus on one thing: converting houses into high-quality HMOs. Letting rooms individually produces far stronger income than a single let, and a well-planned conversion adds value that can be released through a refinance.
Doing that well takes local knowledge, a firm grip on planning and licensing, and a team that delivers on budget. That's what we bring, so our investors get the returns without the learning curve.
Every house we take on is finished to the same standard, valued up at refinance and let room by room. Our investors see the work at every stage and the real numbers at the end, and they come back to us for their next project.
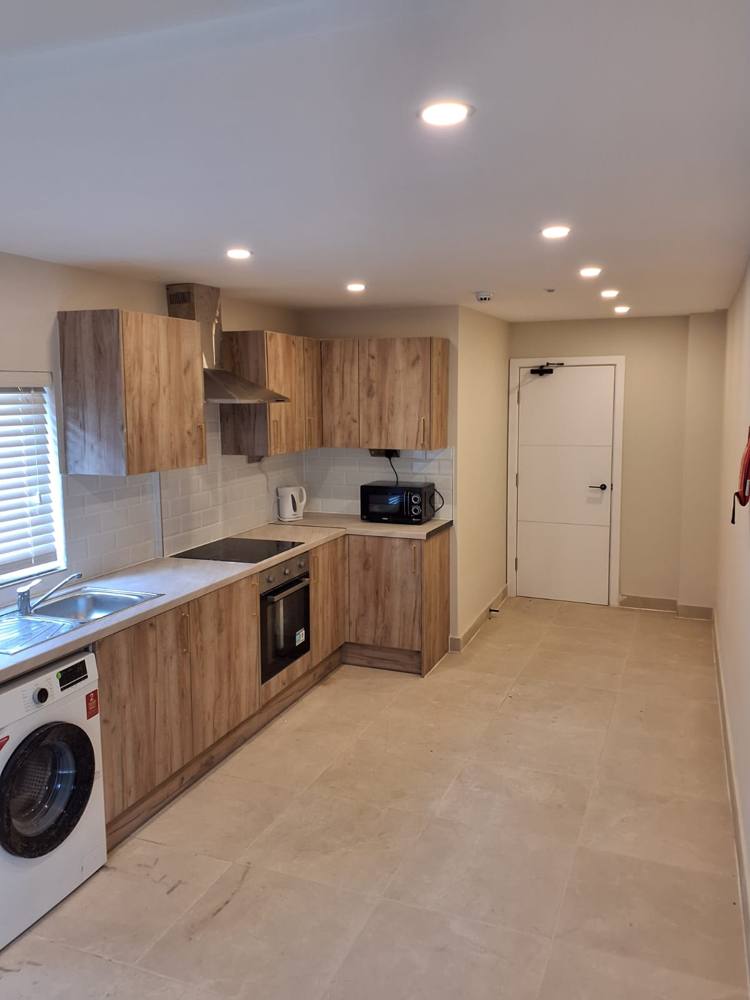 Enfield N9, completed June 2026
Many projects delivered
HMO conversions across London, each one bought, converted, let and refinanced. Greenford, Harrow and Enfield are just a few of the projects we show here.
High-quality finishes
En-suite rooms, fitted kitchens and full fire safety, finished to the same Lera standard in every house.
Strong project returns
25% to 26% cash on cash on the projects featured here, after costs and our fees.
Investors who come back
Our investors return for their next project. One has completed three with us and is now on their fourth.
Past results are not a guide to future returns. Capital at risk.
What you can expect.
Aligned with you
We take no share of your deal. The property and its profit stay 100% yours.
Numbers first
Every deal comes with a full appraisal. If it doesn't stack up, we don't bring it to you.
Compliance built in
Planning, licensing and fire safety are designed in from day one.
Clear communication
Weekly updates during the build and one point of contact throughout.
Our results, shown in the open.
We don't ask you to take our word for it. The projects we feature here are shown with their real numbers: what went in, what came back out and what it earns each year.
Cash on cash, featured projects Click a project to see it
Capital at risk. Targets and examples are not guaranteed, and past results are not a guide to future returns.
Good-quality projects
Every house is finished to the same Lera standard: en-suite rooms, fitted kitchens, full fire safety and HMO certification. Each project page shows the work phase by phase, photo by photo.
Returns we've achieved
The projects featured here returned 25% to 26% cash on cash, in line with the c.25% we aim for. Each one is shown with its real results. Past results are not a guide to future returns.
Delivered to budget and timeline
You get a full costed appraisal before you commit. We put the works out to tender, agree prices up front and manage the build closely to keep each project on budget and on programme.
An expert team
Builders, architects, solicitors, brokers and letting agents we've worked with project after project, led by a team that lives and breathes HMOs.
High-quality HMO deals
We only bring you houses that pass our checks on planning, room sizes, local rents and end value, so every deal starts on solid ground.
Let's talk about your first project.
Your questions, answered.
What investors ask us most before starting an HMO project. Can't find yours? Ask us directly.
HMO basics
What is an HMO?
A house in multiple occupation is a property let to three or more people from more than one household who share facilities such as the kitchen. Each tenant rents their own room, usually with an en-suite, which is why HMOs earn more than a single family let.
Do you buy existing HMOs?
No. We find ordinary houses that are suitable for HMO conversion and convert them. Creating the HMO is what adds the value that lets you refinance and pull most of your cash back out.
Does an HMO need a licence?
In England, an HMO with five or more tenants from two or more households needs a mandatory licence from the local council, and some councils license smaller HMOs too. We handle the application and make sure the property meets the council's standards.
What is Article 4, and does it matter?
Normally a family house can become a small HMO without planning permission. Where an Article 4 direction applies, planning permission is needed. Larger HMOs need planning everywhere. We check this before putting forward any property.
Money and fees
What return can I expect?
Our projects target a cash-on-cash return of circa 25%: your yearly profit after all costs, divided by the cash left in the deal after refinance. That figure already includes our fees. Results depend on the property, interest rates and the refinance valuation, and returns are not guaranteed.
How do your fees work?
We never take a percentage of your deal. The property and its profits are 100% yours. We charge a 2% acquisition fee on the purchase price and a 2% management fee on the property's valuation after the works, and both are included in the returns we quote.
When we put the building works or the bridging finance out to tender, the quotes we receive include an arrangement fee payable to Lera. The conveyancer, mortgage broker, and letting and management company we introduce may also pay us an arrangement fee. These are already built into every price, figure and illustration we show you, so there are no extra costs on top.
How much money do I need?
On our recent six-bedroom project, the investor needed around £225,000 to complete the deal, and around £100,000 remained in it after refinance. We'll give you exact figures for each deal before you commit.
How is the purchase financed?
Usually with a bridging loan covering around 75% of the purchase price plus the build works. Once the house is converted and let, it's revalued and refinanced onto a long-term mortgage, which repays the bridge. We introduce you to brokers who arrange this.
Can I buy through a limited company?
Yes, many investors do. Whether it suits you depends on your tax position, so speak to a property accountant first. We can work with either structure.
Is my money at risk?
As with any property investment, your capital is at risk. Values can fall, costs and interest rates can rise, and rooms can sit empty. We reduce the risk with careful deal selection, managed builds and contingency in every budget, but we can't remove it. Take independent financial advice if you're unsure.
Working with us
How long does a project take?
Around 5–6 months from purchase to a completed, fully let HMO. Finding the right house comes first and depends on the market.
How involved do I need to be?
As little as you like. You approve the deal and sign off key decisions, and we keep you updated. Most investors never need to visit site, though you're always welcome.
Do I need to live near the property?
No. We invest where the numbers work and manage everything on the ground.
Who manages the tenants afterwards?
The property is professionally managed, covering tenants, bills, cleaning and maintenance. You receive the rental income and a monthly statement.
Refer someone. Earn 10%.
Introduce a friend, client, colleague or relative to Lera. For every property they do with us, we'll pay you 10% of our fees.
Anyone who'd like their money working harder.
Three simple steps.
- 1
Introduce them
Fill in the form below, or simply CC us into an email with them on info@lera-realestate.com.
- 2
We take it from there
We'll reach out, book their free strategy call and look after them from the first conversation.
- 3
You get paid
For every property they do with us, we pay you 10% of our fees. Refer them once, earn on every deal.
One introduction, paid on every property.
On a typical project like our worked example, Lera's fees come to about £26,100: 2% of a £475,000 purchase plus 2% of an £830,000 valuation. Your 10% would be around £2,610 for that one property.
The 10% referral fee is based on the fees the client pays us: the 2% acquisition fee and the 2% management fee. It does not include any arrangement fees we may receive when we go out to tender with conveyancers, brokers, contractors or other providers. Referral fees are paid by Lera out of our own fees, so they never add to the client's costs.
Illustrative example only. Actual fees depend on each property's purchase price and valuation.
Just CC us into an email.
Send your contact a quick email introducing us and copy us in. We'll take it from there and make sure you're credited for the referral.
Let's talk about your portfolio.
Book a free 30-minute discovery call. No obligation, just a straight conversation about your goals.
We reply to every enquiry within one working day.